Step-by-Step Medicare Coverage for Skilled Nursing Facility Care
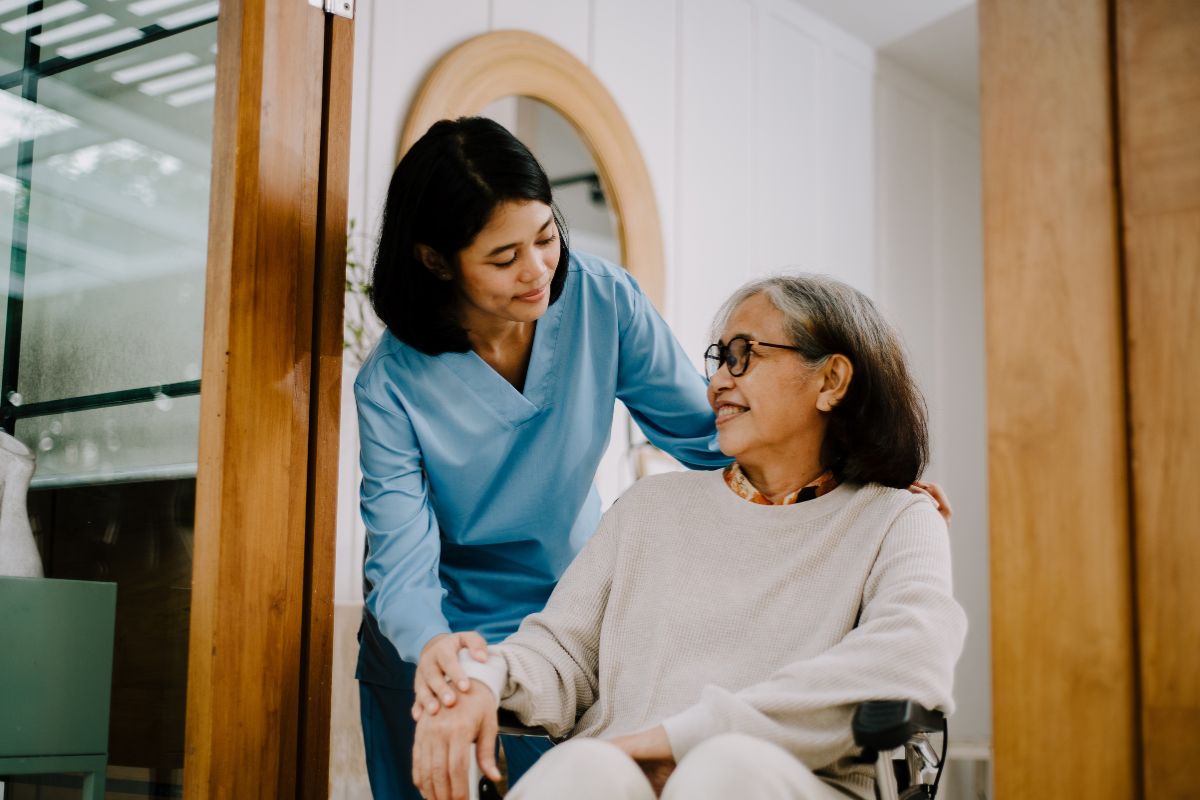
After a hospital stay, some Medicare beneficiaries aren’t quite ready to return home. They may need physical therapy to regain strength, skilled nursing care to recover from surgery, or rehabilitation following a serious illness or injury.
In these situations, a Skilled Nursing Facility (SNF) may be the next step in the recovery process.
Unfortunately, skilled nursing facility coverage is one of the most misunderstood parts of Medicare. Many people assume Medicare pays for any stay in a nursing home, while others believe it won’t help at all. The truth is somewhere in between.
Medicare does provide coverage for skilled nursing facility care, but only when certain requirements are met. Understanding these rules before you need them can help you avoid unexpected costs and make informed decisions about your care.
Let’s walk through how Medicare covers skilled nursing facility care, step-by-step.
Step 1: You Must Have a Qualifying Hospital Stay
The first requirement for Medicare to cover skilled nursing facility care is a qualifying inpatient hospital stay. In most cases, you must have been admitted to a hospital as an inpatient for at least three consecutive days before Medicare will cover care in a skilled nursing facility. This is commonly referred to as Medicare’s 3-day rule.
It’s important to understand that time spent in the hospital under observation status generally does not count toward the three-day requirement. Even if you stayed overnight in a hospital room, observation services are considered outpatient care rather than inpatient care.
Because this distinction can affect your eligibility for skilled nursing facility coverage, it’s worth asking the hospital whether you’ve been formally admitted as an inpatient if you think post-hospital rehabilitation may be needed.
Step 2: Your Doctor Must Determine That Skilled Care Is Necessary
A qualifying hospital stay alone isn’t enough. Your physician must also determine that you need skilled nursing care or skilled rehabilitation services on a daily basis.
The word “skilled” is important here. Medicare covers care that requires the expertise of licensed healthcare professionals, such as registered nurses, physical therapists, occupational therapists, or speech-language pathologists.
Examples of skilled services may include wound care, intravenous medications, rehabilitation after joint replacement surgery, or therapy following a stroke. If your needs involve only assistance with daily activities like bathing, dressing, or eating, Medicare generally does not consider that skilled care.
Step 3: You Must Enter a Medicare-Certified Skilled Nursing Facility
Not every nursing facility participates in Medicare. To receive Medicare coverage, you generally must receive care at a Medicare-certified Skilled Nursing Facility. These facilities meet Medicare’s standards for providing skilled nursing and rehabilitation services.
Before transferring to a facility, it’s a good idea to confirm that it participates in Medicare. Hospital discharge planners often assist with this process, but beneficiaries and family members should still ask questions to understand their coverage.
Step 4: Medicare Begins Covering Eligible Skilled Nursing Care
Once the eligibility requirements have been met, Medicare Part A may begin covering your skilled nursing facility stay. Coverage includes much more than just a room.
Depending on your needs, Medicare may help pay for services such as:
- Skilled nursing care
- Physical therapy
- Occupational therapy
- Speech-language pathology services
- Meals
- Medications provided during your stay
- Medical supplies
- Social services
- Certain medically necessary equipment
The goal of skilled nursing facility care is rehabilitation and recovery, not long-term residence.
Step 5: Understand How Long Medicare Pays
One of the most common questions beneficiaries ask is how long Medicare will cover a skilled nursing facility stay. Medicare coverage is limited.
If you continue to meet Medicare’s eligibility requirements, Part A may cover up to 100 days of skilled nursing facility care during a benefit period. However, that doesn’t mean Medicare pays the entire bill for all 100 days. The amount you pay depends on how long you remain in the facility.
Generally, Medicare covers the full approved cost for the first 20 days. Beginning on day 21, beneficiaries are responsible for a daily coinsurance amount through day 100. If you remain in the facility beyond 100 covered days, Medicare generally stops paying for the stay unless a new benefit period begins and you again meet Medicare’s eligibility requirements.
Step 6: Continue Meeting Medicare’s Requirements
Coverage doesn’t automatically continue simply because you’re staying in the facility. Throughout your stay, Medicare expects that you continue to require skilled nursing care or skilled rehabilitation services.
As your condition improves, the facility regularly evaluates your progress and documents whether skilled care remains medically necessary. If your healthcare team determines that you no longer need skilled services (even if you still need assistance with daily activities) Medicare coverage may end.
This often surprises families who assume Medicare will continue paying until the patient is fully independent. In reality, Medicare’s focus is on whether skilled medical or rehabilitation services are still required.
Skilled Nursing Care Is Different from Long-Term Care
One of the biggest misconceptions about Medicare is that it pays for long-term nursing home care. Generally, it does not. Medicare covers short-term skilled nursing care designed to help patients recover after hospitalization.
Long-term custodial care is different. Custodial care primarily involves assistance with activities of daily living, such as bathing, dressing, eating, and using the restroom. While these services are extremely important, they don’t usually require licensed medical professionals to provide them.
Because of this distinction, Medicare generally does not cover long-term stays in nursing homes when skilled medical care is no longer needed.
What If You Don’t Meet the 3-Day Rule?
If you don’t have a qualifying three-day inpatient hospital stay, Medicare generally won’t cover skilled nursing facility care under Part A. This can happen if you’re treated under observation status rather than formally admitted as an inpatient.
Although observation care may look very similar to an inpatient stay from the patient’s perspective, Medicare treats these situations differently.
What Happens If Medicare Stops Paying?
If Medicare determines that you no longer qualify for skilled nursing facility coverage, the facility must generally notify you before coverage ends.
If you disagree with the decision, you may have the right to request an expedited appeal. During the appeal process, Medicare reviews whether skilled care remains medically necessary based on your medical records and progress.
If coverage ultimately ends, you’ll need to discuss other payment options with the facility if you choose to remain there.
Planning Ahead Can Prevent Surprises
Most people don’t think about skilled nursing facility coverage until a hospitalization makes rehabilitation necessary.Unfortunately, that’s often when confusion arises.
Understanding Medicare’s eligibility requirements ahead of time can help you ask the right questions during a hospital stay and make informed decisions about post-hospital care. Knowing the importance of the three-day inpatient rule, medical necessity, and Medicare-certified facilities can go a long way toward avoiding unexpected expenses.